Buy now, pay later (BNPL) loans are installment loans established at the point-of-sale for the purpose of financing a one-time, unsecured retail transaction. They allow you to finance a purchase with multiple, equal payments instead of one lump sum.

Buy Now, Pay Later
Learn how buy now, pay later loans work and how they may impact your credit.

What is Buy Now, Pay Later?


Buy Now, Pay Later Usage
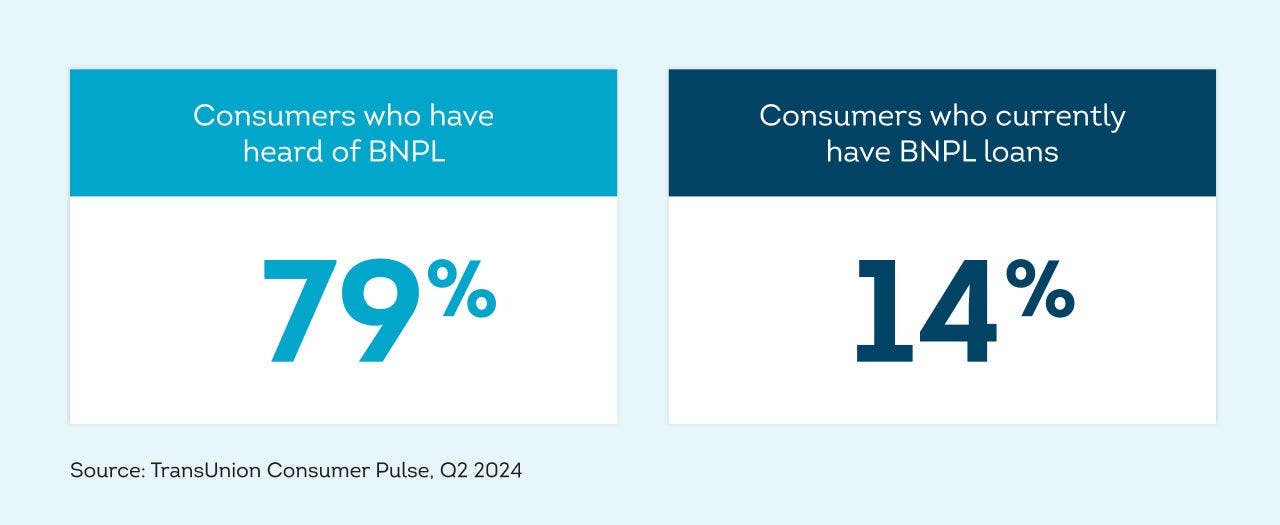
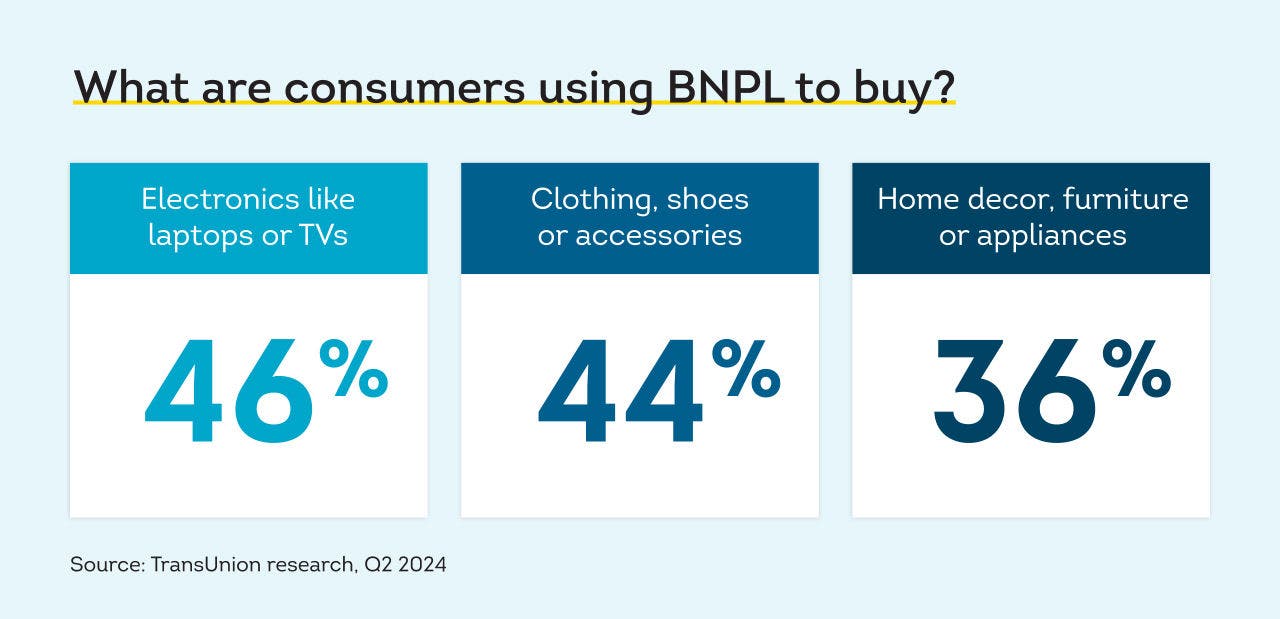
Whether you’ve taken out a BNPL loan or not, you may see more stores offering it at checkout. In 2024 research by TransUnion, here's what we're seeing about U.S. consumers’ familiarity with these loans, and how they’re using them:
Tips for Using BNPL
Whether you’ve taken out a BNPL loan before or are considering trying one for the first time, it’s a good idea to understand how they work.


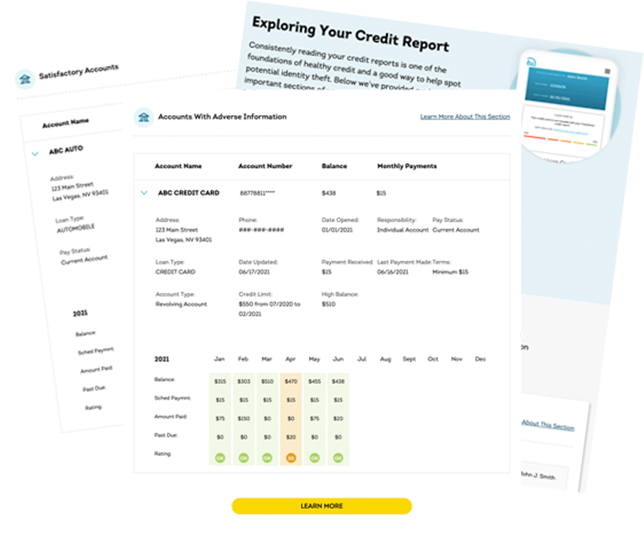
Exploring Your Credit Report
You may see BNPL loans listed among your accounts on your credit report. Use our tool to learn more about each section of your TransUnion Credit Report.
Lenders, Furnishers and BNPL
TransUnion has been working with BNPL lenders for more than five years to ensure data is being thoughtfully incorporated into credit reports.


You have questions, we have answers.
A buy now, pay later (BNPL) loan is an installment loan established at the point-of-sale for the purpose of financing a one-time, unsecured retail transaction. This may include loans referred to as “buy now, pay later” loans that are expected to be repaid over four or six payments, or other longer term loans where consumers may have multiple loans over a relatively short period of time (e.g., over the course of a year).
Not yet, but they may in the future. If you have a BNPL loan, you can check with the company to see if they will be reporting to any of the three nationwide consumer reporting agencies (TransUnion, Experian and Equifax).
Your account and payment history with select buy now, pay later loans (BNPL) may now be seen by lenders when you apply for credit, which could impact certain credit decisions. While some BNPL loan information is on your credit report, it still does not impact your credit score provided by TransUnion. This may change in the future.
When and how BNPL data is adopted by credit score providers may vary. There are different credit scoring companies and they have different versions or models of their credit scores. Not all BNPL companies report their data to credit reporting agencies. If you have a BNPL loan, you can contact them to see if they plan to report.
Once a BNPL company begins furnishing data to TransUnion, only loans originated after that initial date will appear on your credit report.
BNPL data provided to TransUnion does not currently impact credit scores provided by TransUnion.
In the future, some credit scoring models may begin to incorporate BNPL data provided to TransUnion, and missed payments could then impact those scores.
You’ll see a soft inquiry on your credit report if you apply for a BNPL loan. However, lenders do not see soft inquiries, and they do not impact credit scores.
If you have a BNPL loan with a lender that is supplying the data to TransUnion, you’ll see the information within the Accounts section of your credit report. Longer term installment loans made at the point of sale for a single transaction may also appear in this section.
Lenders may report your BNPL account as delinquent if you miss a payment and it remains unpaid for 30 or more days past the scheduled due date.
Your payment history with select BNPL loans may now be seen by lenders when you apply for credit, which could impact certain credit decisions. While some BNPL loan information is on your credit report, it still does not impact your credit score provided by TransUnion. This may change in the future.
If you agreed to make payments every two weeks, the total of two payments may combined and represented as a monthly payment.
The term length will display on your credit report in months, rounding up to the nearest total month. For example, a typical pay-in-four loan that has a down payment and three payments over six weeks will display on a credit report with a term of two months.
Select BNPL loans and other point-of-sale loan data on your TransUnion credit report can be seen by lenders, which may impact some credit decisions.
The extent to which BNPL loans will impact credit decisions may depend on the type of credit you’re applying for and the individual lender. How much importance lenders place on BNPL loan information when evaluating creditworthniness may vary.
The BNPL loan information, like any other installment loan, will remain on your credit report after you pay it off. An account that was in good standing with a history of on-time payments when you closed it will typically stay on your credit report for up to 10 years. Accounts with adverse information may stay on your credit report for up to seven years.
BNPL is an evolving area of pesonal finance and lenders are gradually integrating data into the credit reporting ecosystem, which means more lenders may use this information to help evaluate your creditworthiness. Ultimately, it can be a way to show lenders you pay your installment loans back on time.
Other nationwide consumer reporting agencies (Experian or Equifax) may have different timelines for presenting BNPL data, so you may see differences between your credit reports.
If you recently paid your BNPL loan, you may not see that payment reflected on your credit report until your next monthly statement. Credit reports update when lenders provide new information to the credit reporting agencies, so you may not see changes reflected immediately in your report. However, if you want to dispute an inaccuracy around your BNPL installment loan, you can do so for free through the TransUnion Service Center.
TransUnion is working directly with BNPL companies as they move towards reporting this data. Many of these companies have not reported to credit reporting agencies before, so they need time to build both furnishing and disputes processes. It’s important to get these processes right to ensure accuracy and protect consumers.
In the interim, consumers will only see BNPL loans on their credit reports from the BNPL companies that are ready to provide this data and willing to furnish it to TransUnion.
You may receive communication from TransUnion regarding BNPL installment loans. If you do not have any BNPL installment loans, these communications will not apply to you.
BNPL installment loans may appear on credit reports differently based on the nationwide consumer reporting agency (also known as a credit bureau). Please visit the websites of the other credit bureaus to learn more about their treatment of BNPL installment loan accounts in their respective credit reports.


Information for Good®.
Connect with us


