

Key Takeaways:
- Closing a credit card or paying off a loan does not automatically remove the account from your credit history.
- How long a closed amount remains on your credit report depends on the status of the account or type of information.
- Generally, accounts closed in good standing remain on your credit report for up to 10 years, while negative information can remain for seven years, but there are some exceptions.

Disclosure:
This post only contains educational information. No financial, tax or legal advice.
This information is for educational purposes only and we do not guarantee the accuracy or completeness of this information. This information does not constitute financial, tax or legal advice and you should consult your own professional adviser regarding your situation. This website may contain links to third party websites. We are not responsible for their content or data collection. Trademarks used in this material are property of their respective owners and no affiliation or endorsement is implied.
You might assume that once a credit account is closed, it disappears from your credit report. In reality, closed accounts can remain part of your credit history even after they are closed. Understanding how long closed accounts remain on your credit report and how they affect your credit can help you make more informed decisions.
What is a closed account on a credit report?
Closed accounts, even though they are inactive, may remain on your credit report. For how long depends on the type of account and whether they had a positive or negative history.
When do accounts fall off your credit report?
Accounts in good standing with a history of on-time payments generally remain on a credit report for up to 10 years after closure. However, negative information, like late payments, charge-offs and collections, typically remain on your credit report for up to seven years from the original delinquency date.
Are paid collections removed from your credit report?
Whether paid or unpaid, a collections account may stay on your credit report for up to seven years. One special case is for New York residents: paid collections will fall off their credit reports after 5 years.
| Information Type | How Long the Information Stays on Your Report? |
|---|---|
| Accounts closed in good standing | 10 years |
| Missed payments | 7 years |
| Collections | 7 years |
| Bankruptcies | Chapter 7: 10 years
Chapter 11: 10 years Chapter 12: 10 years Chapter 13: 7 years |
Special Cases to Know About
Bankruptcies
Bankruptcies stay on your credit report for different lengths of time depending on the type. Generally, chapter 7, 11 and 12 bankruptcies will stay on your report for 10 years from the date the bankruptcy was filed. However, TransUnion will remove voluntarily dismissed bankruptcies after seven years. A Chapter 13 remains on file for seven years. A Chapter 13 bankruptcy falls off a credit report faster because people agree to pay some of the debt back through a payment plan. However, if the repayment plan is not completed, it will remain on your report for 10 years. After the allotted seven or 10 years, the bankruptcy will automatically fall off your credit report.
Medical debt
Medical debt collections will be removed from your credit report when paid in full. Unpaid medical debt will not appear on your credit report for a year from the date of the original delinquency. This gives you time to work with your insurance or healthcare providers to address the debt before it is reported on your credit file. Medical collection debt under $500 does not appear on credit reports. There are also state-specific limitations on the reporting of medical debt or medical debt collections on credit reports.
Closed by you vs. closed by the lender
A voluntary account closure is when you choose to close a credit account on your own. This typically happens with revolving lines of credit, like credit card accounts. Revolving credit gives you access to an always available line of credit. As long as the account is in good standing, you can typically close the account with the lender.
With installment loans, like a mortgage or auto loan, you typically have set, fixed payments each month with a designated end date or last payment for the loan. After making your final payment, your account with the lender will be closed.
An involuntary account closure can happen when a lender closes an account without your request. This may be because of missed payments, a violation of the account agreement or inactivity on the account. You should receive a notice from the lender if they plan to close the account. You can contact your lender if you have any questions.
Do closed accounts affect your credit score?
Closing accounts can impact your credit score, but by how much can depend on the credit scoring model used and your personal credit history. There are different credit scoring models and while they tend to focus on similar factors, how much they weigh factors can vary. , how much they weigh factors can vary.
Depth of credit is an influential factor that considers your credit mix and your experience with credit. A long history of credit with a diverse mix of active accounts can help your score. Generally, credit score calculations tend to favor active accounts in good standing, so you may see an initial negative impact to your credit score when an account is closed.
Credit Score Factors
Here are the factors that make up a VantageScore® 3.0 credit score and their relative impact:
- Payment history
- Utilization
- Balances
- Depth of credit
- Recent credit
- Available credit
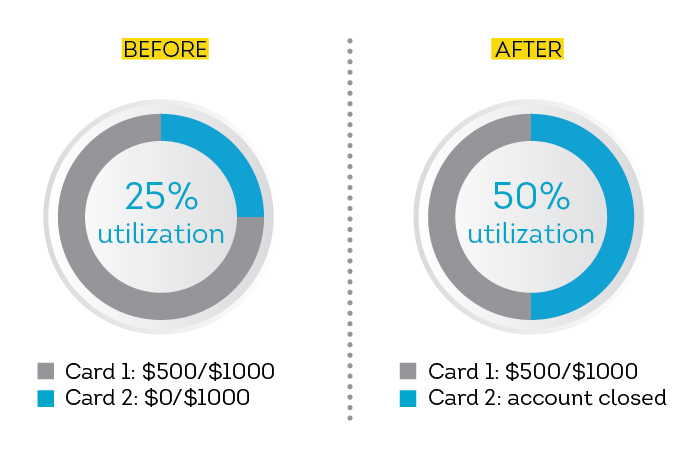
If closing a credit card account, give consideration to your credit utilization. Credit utilization is a measure of how much credit you’re actively using and is an important component of your credit score. It's calculated by adding up your total balances across your credit cards and dividing that by your total credit limits across all credit cards. Generally, the lower your credit utilization, the better it is for your credit score.
When you close a credit card, you lose access to the available credit limit. This will lower total credit limit, which can increase your credit utilization. If you still have balances on your open credit card accounts, this could result in a further increase in your credit utilization.
How do I get closed accounts off my credit report?
Wait for them to fall off
- Most closed accounts are removed automatically after the applicable reporting timeframe.
- Reading your credit report regularly can help you stay aware of when information is set to be removed from your report.
Dispute incorrect information
- If there is an account on your credit report that is not yours because of fraud, you can dispute it.
- Disputes are free and can easily be done online.
- In addition to your credit dispute, you should consider adding a credit freeze to your credit report, which can help prevent new accounts from being opened in your name.
What you cannot remove
- Both positive and negative information, if accurate, will remain on your credit report for the allotted time.
Pro Tip:
Think your identity may have been stolen? Learn how you can help protect your credit and personal information in our blog: What To Do if Your Identity Is Stolen: Steps to Take
Should you close old credit accounts?
If you’re considering closing an account, make sure to weigh the pros and cons. There's no right choice for everyone—how you manage your credit and accounts will vary based on your personal circumstances and financial goals.
Pros of closing a credit account
- Simplified finances: As long as your account is paid off, closing an account means you no longer need to keep track of the balances and payment schedule.
- Avoiding annual fees: Some premium credit cards have an annual fee — closing the account can save money.
- Reducing temptation to overspend: Some people may find they are more likely to overspend if they keep a credit account open and have access to the credit line.
Cons of closing a credit account
- Credit utilization impact: If you have balances on other credit cards, canceling a credit card account may cause your credit limit to decrease and consequently cause your credit utilization to increase.
- Potential credit score impact: A rise in your credit utilization could impact your credit score. Losing an active credit account in good standing may also cause an impact to your credit score. This is part of the “depth of credit” credit score factor, which accounts for 21% of your VantageScore® 3.0 credit score.
How to maintain healthy credit after closing an account
Whether you close an account or choose to keep it open, it’s important to maintain healthy credit habits. Make sure you make all your payments on time, try to keep your balances as low as possible and aim to limit new credit applications. Practicing these habits can help you build a healthy credit history.
FAQs
Typically, accounts that are closed in good standing will stay on your credit report for up to 10 years. Accounts closed with adverse information, like accounts with reported late payments or those sent to collections, are generally removed from your credit report after seven years.
Closing an account can impact your credit score, but if and by how much depends on your individual credit history. Credit depth is an influential factor that considers your credit mix and your experience with credit. A long history of credit with a diverse, active mix of accounts can help your score. If you have different types of credit and are managing them well, like a credit card, car loan, and others, it can show lenders you can manage credit responsibly.
Credit scoring models favor active accounts in good standing, so closing an account may have a temporary negative impact on your credit score. You should also consider any current balances you have on credit cards before closing a credit card account — your credit utilization may change, which is an important credit score factor.
Accounts will fall off your credit report on their own after the allotted time period. If an account is inaccurate or the result of fraud, you can dispute the account.